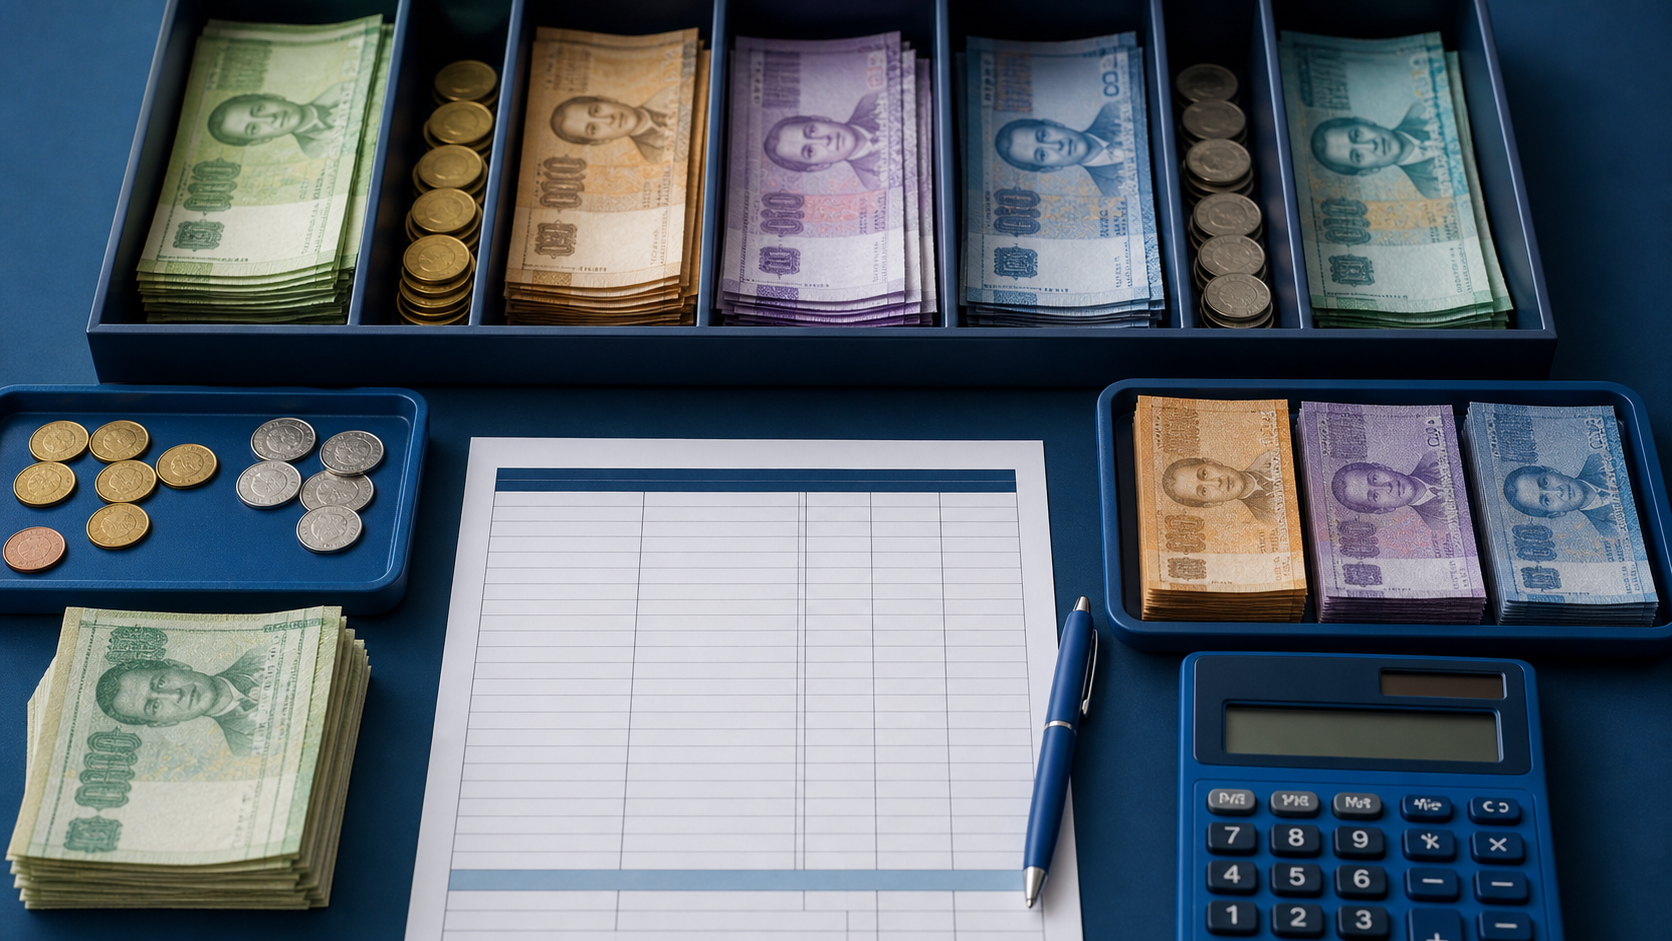
A running total is a single number nobody can check. A denomination breakdown is a set of small claims that anyone can test against the physical cash, which is why the Change Counter calculator keeps every row visible instead of hiding the working.
If your record says the drawer held a specific total and nothing else, a dispute has nowhere to go. If it says how many of each denomination, the disagreement can be narrowed to one stack.
1. Why Denomination Order Matters
Counting mixed cash as one running total means every piece must be added to a number you are holding in your head. Counting by denomination means counting pieces, which the human eye and hand do well, and letting multiplication happen once per row. The workload drops sharply.
The Verification Benefit
The real gain is checkability. A supervisor can verify one denomination in seconds without redoing the whole count, and a disputed figure narrows to a single stack. That is impossible with a running total, however carefully it was produced.
- Count pieces, not values, and multiply once per denomination.
- Work from the highest value down while attention is sharpest.
- Keep each denomination physically separate throughout.
- Produce a breakdown, not just a total.
2. Face The Notes One Way
Orienting every note the same way before counting is not tidiness for its own sake. A note of the wrong value, a foreign note or a note folded around another becomes visible without being looked for, which converts an active check into a passive one.
Counting A Faced Stack
Count faced notes in consistent groups, typically ten or twenty five depending on the denomination, then count the groups. The same batching logic that speeds up coin counting applies to notes, and it limits the damage from an interruption in exactly the same way.
- Face every note the same direction before counting.
- Count in fixed groups rather than one continuous run.
- Watch for a note that will not lie flat, it is often two.
- Set damaged and suspect notes aside before counting.
3. Group Coins By Value
Coins should be separated into single value groups before any counting starts. Sorting by diameter is the fastest route to that, since size is quicker to judge than a printed value, particularly on worn coins under artificial light.
Confirming Each Group
Once sorted, check one coin from each group against its value before batching. Sorting by size occasionally puts two similar coins together, and confirming the group takes a second whereas discovering it after entry costs a full recount. Detail in counting coins quickly.
- Sort by diameter first, then confirm value per group.
- Batch each group into a consistent quantity.
- Keep bimetallic coins in their own group.
- Remove foreign and damaged pieces before entry.
4. Enter One Row At A Time
Complete a denomination fully before starting the next. Count it, enter it, move the physical cash aside. The moving is the part people skip and the part that prevents the most common error in all cash work, which is entering the same stack twice.
Avoiding Row Confusion
Denomination rows sit close together in any list, and entering a quantity one row above or below the intended one is easy under time pressure. Reading the row label rather than its position guards against this, especially when the display order is switched between high to low and low to high.
- Finish one denomination completely before starting the next.
- Move counted cash out of the working area immediately.
- Read the row label rather than trusting its position.
- Leave unused rows at zero rather than filling them.
5. Read Subtotals Aloud
Speaking a subtotal engages a different check than reading it. Forty notes of fifty is two thousand, and saying that aloud makes an error obvious in a way that scanning past it does not. Where two people are counting, it also gives the second person something concrete to confirm.
The Second Person Role
A verifier who watches a count adds little, because they tend to follow rather than check. A verifier who hears each subtotal and confirms it against the physical stack is doing real work. Structure the role that way and dual counting becomes worth the time it costs.
- Say each quantity and subtotal aloud when a verifier is present.
- Have the verifier confirm against the physical stack, not the screen.
- Recount the cash before changing any entered figure.
- Scan the full subtotal column before accepting the total.
6. Handle Duplicate Face Values
Several currencies circulate the same face value as both a note and a coin. They are different physical objects with different handling, storage and banking treatment, so they need separate rows even though their value is identical.
Keeping Them Straight
Enter each on the row matching the physical format in your hand rather than the one that appears first. Both add into the same total, so nothing is lost, but the breakdown then reflects what was actually in the drawer, which matters when the deposit is strapped and bagged.
- Read the note or coin label under each value before entering.
- Never merge a note quantity and a coin quantity into one row.
- Check the breakdown reflects the physical mix before printing.
- Use the type filters to work one format at a time.
7. Verify With A Second Pass
For amounts that justify it, run a blind second count. The second counter works from the physical cash without seeing the first result, and the two breakdowns are compared afterwards. Agreement across every row is far stronger evidence than agreement on a total.
Resolving A Disagreement
Where the two counts differ, only the disputed denominations need recounting. That is the practical payoff of a denomination breakdown, and it turns a full recount into a two minute exercise on one or two rows.
- Run the second count blind rather than as a review.
- Compare row by row, not total to total.
- Recount only the denominations that disagree.
- Record which rows required a third count.
8. Report The Breakdown
Finish by producing a record that shows quantity, denomination and subtotal for every row. That document is what makes the count defensible, and it costs nothing beyond pressing print or export once the count is already in front of you.
Choosing A Format
Print when the record is filed on paper with a sales report or deposit slip. Export CSV when it feeds a spreadsheet or ledger. Do both when the count supports a banking deposit, since the printed sheet travels with the paperwork while the export supports later analysis. Template guidance is in building a daily cash count sheet.
- Record quantity, denomination and subtotal for every active row.
- Complete the counted by and verified by fields before printing.
- Export CSV where the figures feed a spreadsheet.
- File the breakdown with the related sales or deposit record.
Worked Example
A drawer contains notes and coin including one face value that circulates in both formats. Counting by denomination keeps the two apart while adding both into the same total.
| Denomination | Quantity | Subtotal |
|---|---|---|
| 50 note | 12 | 600.00 |
| 20 note | 31 | 620.00 |
| 10 note | 24 | 240.00 |
| 5 note | 18 | 90.00 |
| 2 coin | 46 | 92.00 |
| 1 coin | 73 | 73.00 |
The breakdown totals one thousand seven hundred and fifteen. Because each row stands alone, a supervisor can verify the twenty note stack in seconds without touching anything else, which is exactly what a total on its own would prevent.
Final Checklist
- Separate notes from coins before counting anything.
- Face every note the same direction.
- Sort coins by size, then confirm each group value.
- Count and enter one denomination at a time.
- Move counted cash out of the working area.
- Read subtotals aloud when a verifier is present.
- Keep duplicate face values on their correct rows.
- Produce and file a full denomination breakdown.
The method costs a little more time at the start and removes the recounts at the end. For anyone counting regularly, that trade is strongly in favour of denomination order.
Frequently Asked Questions
Is it faster to count highest to lowest or the other way?
Highest to lowest is generally better because the largest financial risk is handled while concentration is at its best, and an error in a high value row moves the total far more. Low to high suits situations where small coin dominates. Either works provided you stay consistent.
What if a denomination is not listed?
Use the Other cash field for genuine physical value that no row covers, such as a commemorative piece or a rounded amount carried over. Keep cheques, vouchers and card settlements out of it, since including them makes the total stop representing cash.
Do I need to record denominations, or is the total enough?
A total alone is enough only until it is questioned. The breakdown is what lets you answer a bank query, resolve a variance to a single stack, or prove a deposit composition. It costs one keystroke to keep, which is a small price for the only evidence you will have.
Put It Into Practice
Count your next drawer strictly by denomination and keep the breakdown. The first time somebody queries a figure, that sheet will do the work that memory cannot.
Keep reading: Multi Currency Cash Counting Best Practices, How To Balance A Cash Register At Closing, How To Prepare A Business Bank Deposit, Cash Handling Procedures Every Business Needs. The full cash counting guide library collects all fifteen walkthroughs, and the Change Counter calculator is always one click away.